SolGuruz Logo
Pricing

Buy Now Pay Later App Development Company

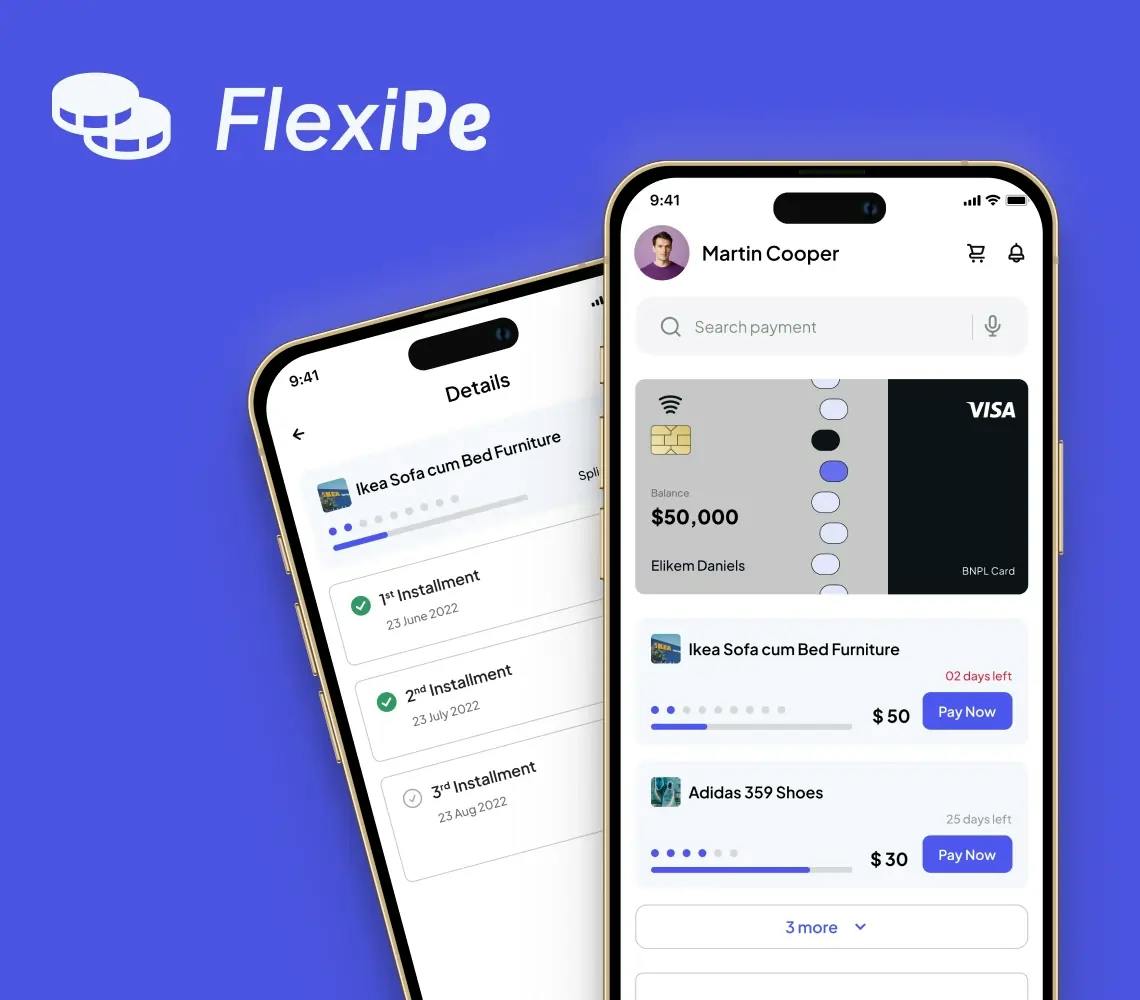
SolGuruz is a Buy Now Pay Later app development company that builds the full BNPL stack, from the shopper app and merchant checkout to the credit decisioning, settlement, and compliance behind them. We have shipped a production BNPL app (FlexiPe) against CFPB Reg Z, KYC and AML, and PCI-DSS Level 1 practices, so we scope your build from experience, not theory.

Trusted by Startups and Enterprises Worldwide

Custom Software Development Success Stories

Hear It Directly From the Founders Who Built With Us

Real founders, CEOs, CTOs, and product owners behind 102+ shipped products across 14 industries share what working with SolGuruz looked like. Every story is one of 133+ independently verified client reviews across Clutch, Google, Glassdoor, and other platforms, averaging 4.9 ★★★★★ ratings.

Frame 01 / 04

Custom Software Solution Development / Driver Dashboard & Invoice Automation for Food Service Company

SolGuruz has delivered a solution that has reduced 90% of manual efforts through automation and provided real-time insights for supplier fulfillment and order volume trends. The team is responsive to requests and changes, and their proactive approach to problem-solving has stood out.

Summarized from Gary Boyd's Clutch review

Gary Boyd

CEO and Owner, Tasty Food Guys | Florida, USA

Read Clutch Verified Review
Tasty Food Guys

what we build

BNPL App Development Solutions We Deliver

BNPL is not one product. It is a lending platform for providers, a checkout feature for merchants, and a credit engine underneath both. We build across all of it, tailored to your market and plan types.

For BNPL Providers and Lenders

You own the credit product. We build the shopper app, decisioning, settlement, and collections, and we build them to comply.

Consumer Pay-in-4 and Instalment Apps

Consumer Pay-in-4 and Instalment Apps

Klarna-style and Affirm-style apps with real-time approval, flexible plans, autopay, and a shopper experience people trust with their money. See our guide to building a BNPL app like Klarna.
Card-Linked and Virtual-Card BNPL

Card-Linked and Virtual-Card BNPL

BNPL delivered through a virtual or linked card, so shoppers can pay in instalments anywhere the card is accepted, with activity tracked per card.

White-Label BNPL Platforms

White-Label BNPL Platforms

A branded BNPL product you can take to market fast, built on a credit rail you control. See our approach to white-label software solutions.
B2B BNPL and Trade Credit

B2B BNPL and Trade Credit

Net-terms and instalment financing for business buyers, with approval, invoicing, and reconciliation built for higher-ticket B2B orders.

For Merchants and Platforms

You want to offer instalments without becoming a lender. We integrate BNPL into your checkout and keep your storefront yours.

BNPL Checkout Integration

BNPL Checkout Integration

Add an instalment option to an existing store or point of sale through a clean SDK or plugin, with the provider carrying the credit risk.

Marketplace and Split-Payment Flows

Marketplace and Split-Payment Flows

Split-payment and instalment flows for marketplaces, similar to a split payments app like Tamara, with payouts routed to the right sellers.

Vertical and Supporting Platforms

The credit engine and back office that make a BNPL product work, plus BNPL tuned for specific verticals.

Credit Decisioning and Underwriting Engines

Credit Decisioning and Underwriting Engines

Real-time approve or decline, spending limits, fraud checks, and the scoring logic that keeps default losses below fee revenue.

Merchant Portal, Settlement, and Reconciliation

Merchant Portal, Settlement, and Reconciliation

Merchant onboarding, a settlement dashboard, ledgering, and reconciliation so every payout and fee, from the merchant discount rate (MDR) and interchange to late fees, is accurate and auditable.

Repayment, Collections, and Dunning

Repayment, Collections, and Dunning

Auto-debit with retry logic, structured reminders, late-fee handling where legal, and collections on defaults.

Vertical BNPL

Vertical BNPL

BNPL tuned for a sector, from healthcare and patient financing to high-ticket retail, travel, and education instalments.

Ready to Build Your BNPL Product?

Talk to a team that has shipped a production BNPL app, from decisioning to compliance and launch.

our services

Our BNPL App Development Services

Our buy now pay later app development services span the full build, from the first scoping call to post-launch iteration, so you are not stitching together separate vendors for app, backend, and compliance.

free resource

Building a BNPL Product? Start With the Complete Build Guide

Covers the whole fintech build: architecture, ledgers and reconciliation, PCI DSS, KYC/AML, GDPR, PSD2 and Open Banking, UX that balances security against friction, plus QA, fraud testing, and monitoring. Free to download.

19+ Downloads
FinTech App Development
Ebook

FinTech App Development: Building Secure Financial Software from Scratch

A practical eBook for founders, CTOs, and product leaders on building secure financial systems that users trust and regulators approve.

AI and ML

AI Capabilities We Build Into BNPL Apps

We add AI where it earns its place in a BNPL product, from the credit decision at checkout to collections after it. Each capability below is built into the platform, not bolted on after launch, and backed by our AI development team.

AI Credit Decisioning and Underwriting

  • Approve or decline in real time using alternative data and machine-learning scoring, not just static rules.
  • Reach thin-file and new-to-credit buyers more accurately while keeping default risk in check.

Real-Time Fraud Detection

  • Flag risky applications and transactions with ML models and device signals at the moment of checkout.
  • Cut losses from account takeover, synthetic identities, and first-party fraud.

Dynamic, Risk-Based Spending Limits

  • Set and adjust each user limit automatically from repayment behavior and live risk signals.
  • Grow limits for reliable customers and tighten them where risk rises.

Smart Collections and Repayment Prediction

  • Predict which customers are likely to miss a payment before the due date.
  • Time the reminder and pick the right channel to lift on-time repayment and lower defaults.

Checkout Personalisation and Plan Offers

  • Recommend the plan most likely to convert for each shopper at checkout.
  • Lift conversion and average order value with offers tuned to the buyer.

Conversational AI Support

  • Handle repayment questions, plan changes, and disputes with an AI assistant that knows the account context.
  • Reduce support load while keeping responses accurate and on-policy.
Put AI to Work in Your BNPL Product

From smarter credit decisions to fraud detection and personalised checkout, we build the AI that moves your numbers.

compliance

Compliance We Build To

A BNPL app is regulated consumer credit. We treat compliance as an architecture input from day one, and we build to comply rather than bolting it on at the end. For the deeper view, read our fintech secure product building playbook.

CFPB Regulation Z

CFPB Regulation Z

US BNPL lenders must now provide consumer protections similar to credit cards, including dispute resolution and refund handling. We build the product flows that support it.

State Money Transmitter Requirements

State Money Transmitter Requirements

Moving and settling funds can trigger money transmitter licensing that varies by state. We design the architecture around your legal setup and go-to-market.

KYC and AML

KYC and AML

Identity verification and Anti-Money-Laundering screening are built into onboarding through specialist providers, with ongoing monitoring for suspicious activity.

PCI-DSS

PCI-DSS

On our FlexiPe build we followed PCI-DSS Level 1 practices with a segmented cardholder-data environment. For the deeper detail, see our answer on PCI-DSS requirements for fintech apps.

integrations

Integrations a BNPL Platform Depends On

A BNPL platform is a set of services around a ledger. These are the integrations we wire in so the product moves money safely and decides credit in real time.

Payment Gateways and Processors

Payment Gateways and Processors

Stripe, Adyen, or a bank gateway to move funds and tokenize card data, so raw card numbers never touch your systems and PCI scope stays small.

KYC and AML Providers

KYC and AML Providers

Identity verification and screening wired into onboarding, so credit is only granted after a user is verified.

Credit Bureaus and Scoring

Credit Bureaus and Scoring

Decisioning inputs and, where applicable, repayment reporting through providers such as Experian, TransUnion, and Equifax.

Accounting and Reconciliation

Accounting and Reconciliation

Systems that track repayments, fees, and merchant payouts accurately, so finance and compliance always reconcile.

Tech Stack We Use for BNPL Apps

We keep the stack boring and proven, because a BNPL app is won on decisioning and compliance, not on chasing trends. For the full layer-by-layer breakdown, read our guide on how to build a BNPL app.

Our BNPL App Development Process

We follow a defined process so compliance and credit risk are handled early, not discovered late. Each stage has a named deliverable and a clear owner.

  1. 01 / 05

    Market and Regulatory Research

    We define the target user, merchant category, and geographies, and map the compliance obligations for each, because regulation shapes scope from the start.
  2. 02 / 05

    Concept and Architecture

    We lock the feature set, the build-versus-integrate calls on the risk engine, the budget, and the release scope, then design the services around an auditable ledger.
  3. 03 / 05

    Design and Development

    We design the shopper, merchant, and admin flows for trust, then build the apps and backend with KYC, gateway, and decisioning integrations wired in and security first.
  4. 04 / 05

    Testing and Compliance QA

    We test data protection, the full repayment lifecycle including failure paths, and performance under load, and verify controls against Reg Z, KYC and AML, and PCI-DSS.
  5. 05 / 05

    Launch and Optimization

    We ship to the app stores, onboard the first merchants, and stand up monitoring, then tune approval rates, default rates, and conversion as real transactions flow.

AI-native engineering

Our AI-Native Engineering Standards

AI-native by practice, engineer-led by principle. We use AI-assisted tools at every step of design, development, launch and growth, and a senior engineer still owns every architecture decision, every security review and every line that reaches production.

  1. 01Design

    • AI-Assisted Discovery and Prototyping

      We use AI to map requirements, user stories and workflows, and to turn them into a clickable prototype your stakeholders can test before production code is written.

      Engineer-ledOur team runs discovery with you and agrees the scope before anything is built.

    • Pixel-Perfect UI/UX and Design Systems

      AI speeds up layout variations, accessibility checks and design-to-code handoff, on a shared design system in Figma.

      Engineer-ledDesigners make every design decision, and every screen is built to match the approved design on every device.

    • Architecture-First Planning

      We settle the architecture, data model, state management and integrations before the build starts, so the product scales without a rewrite.

      Engineer-ledA senior engineer owns every architecture decision.

  2. 02Build

    • AI-Assisted Development, Human-Owned Code

      Our developers use Claude Code, GitHub Copilot and Cursor for scaffolding, boilerplate and repetitive patterns.

      Engineer-ledSenior engineers own the logic, and a developer reviews every AI-generated change.

    • Coding Standards, Git Flow and Peer Review

      Code follows agreed standards and a Git Flow branching model, and AI-powered review flags issues on every commit.

      Engineer-ledA second developer reviews every change before it merges.

    • Secure and Compliant by Default

      We work under ISO 27001 and ISO 9001 certified processes, build to SOC 2-aligned controls, and add HIPAA-aligned safeguards where health data is involved.

      Engineer-ledA senior engineer owns every security review. Independent security agencies run penetration tests, and we remediate their findings.

  3. 03Ship

    • AI-Generated Tests and Manual QA

      AI generates unit tests, edge cases and regression suites from the codebase.

      Engineer-ledQA engineers test the real user flows by hand before every release.

    • Static Analysis and CI/CD Pipelines

      Static code analysis scans every commit, and CI/CD pipelines build, test and deploy across development, staging and production.

      Engineer-ledEngineers set the quality gates the pipeline enforces and fix what the scans flag.

    • Phased, Monitored Releases

      Alpha and beta builds go to internal and external users first, and releases roll out in phases with a rollback plan.

      Engineer-ledYou get a demo build after every sprint and review it with the team.

  4. 04Grow

    • Monitoring, Analytics and Performance

      Crash reporting, performance monitoring and usage analytics are in place from launch day, and for mobile apps we track Google Play and App Store analytics too.

      Engineer-ledOur engineers keep checking crash reports and store analytics for the life of the product, so it stays stable long after launch.

    • Data-Driven Iteration and Growth

      We plan in two-week sprints and prioritise new features from user feedback and analytics, not guesswork. For clients without an in-house marketing team, we also run the product growth strategy after launch.

      Engineer-ledDaily stand-ups and sprint demos keep you in every decision about what ships next.

    • Documentation, Ownership and Ongoing Support

      AI keeps API references and technical docs in sync with the code, and maintenance plans keep the product secure and up to date.

      Engineer-ledYou get full repository access and IP ownership, and one in-house senior team stays accountable for the outcome.

cost

How Much Does BNPL App Development Cost?

BNPL app development cost tracks scope more than anything else, and the biggest driver is how much of the credit and risk engine you build versus integrate. A lean first version can reach an early launch in 2 to 4 months, typically $30,000 to $50,000. A production-grade, regulated platform runs 8 to 14 months and costs several times more, often $150,000 to $300,000 or more.

Lean BNPL MVP

Lean BNPL MVP

One platform, a simple Pay-in-4 flow, and an integrated decisioning provider. The fastest route to validating the product with real users. Typically $30,000 to $50,000.

Growth BNPL Platform

Growth BNPL Platform

A native app, a merchant console, and integrated decisioning with deeper compliance and several integrations. The step up from an MVP toward a full production build. Typically $50,000 to $150,000.

Production-Grade Platform

Production-Grade Platform

Native apps, a merchant console, in-house decisioning, and full compliance. The build for a fintech launching a real BNPL product. Typically $150,000 to $300,000 or more.

Cost Drivers

Cost Drivers

Number of surfaces, native versus cross-platform, the build-versus- integrate call on decisioning, and the depth of compliance work. See the full breakdown in our cost to develop a BNPL app like Affirm guide.

Ranges are indicative and depend on your feature set, platforms, and integrations. We give a line-item estimate during scoping.

Build a BNPL Product That Actually Scales

As a BNPL development company that has shipped in production, we build BNPL products from credit decisioning to compliance and launch.

industries

Industries We Build BNPL For

BNPL fits anywhere a purchase or a bill is large enough that paying over time changes the decision. We build it for the sectors where that matters most.

  • Retail and E-commerce

    Checkout BNPL that lifts conversion and average order value, and reduces cart abandonment, for online and in-store retail.

  • Healthcare and Patient Financing

    Instalment plans for treatments and procedures, so patients can spread costs and providers get paid upfront.

  • Travel and High-Ticket

    BNPL for travel, electronics, education, and other high-ticket purchases where instalments drive the sale.

  • B2B and Marketplaces

    Trade credit and net-terms financing for business buyers, and split-payment flows for marketplaces.

Why SolGuruz for BNPL App Development?

We combine shipped BNPL experience, real compliance depth, and one team across the whole build, so you build with a team that has done this before.

Here's why founders trust us to build their BNPL product:

  • A Shipped BNPL Product

    We built and launched FlexiPe, our BNPL app case study, a production BNPL app for a US fintech, in 8 to 10 months. We scope your build from that experience, not from theory.
  • Compliance Built In

    We build to comply with CFPB Reg Z, KYC and AML, and PCI-DSS Level 1 practices, so the regulated parts are handled from the architecture up.
  • The Credit Engine, Not Just the UI

    We build the decisioning, limits, settlement, and collections that make a BNPL product work, which is where most teams underestimate the work.
  • Proven Delivery

    SolGuruz has shipped 102+ products across 14 industries with a 99.9% delivery rate, backed by ISO 27001 and ISO 9001 certified processes. See where we rank among BNPL app development companies.
  • One Team, One Build

    App, backend, decisioning, and compliance under one roof, so you are not integrating separate vendors and hoping the seams hold.

What Our Clients Say

Read what founders and product teams say about building with SolGuruz.

Top Clutch Software Developers - Financial Services, Ahmedabad
Top Clutch Software Developers - Financial Services, India
Top Clutch App Development Company - Financial Services, Ahmedabad
Top Clutch Web Developers - Financial Services, Ahmedabad
Clutch Fall Champion 2024
Software & SaaS

SaaS Platform Redesign Services for Sales Promoting Platform

The platform looks better than before and is appreciated by the end customers, thanks to SolGuruz. The team uses Slack for communication and has been effective so far. Their dedication and proactivity impress the client.

Robin Singhvi's review for SolGuruz

Summarized from Robin Singhvi's Clutch review

Robin Singhvi, CEO, SmartCue

IndiaMumbai, India

Jan. 2022 - Ongoing
Software & SaaS

UI/UX Design & Development for Software Community Platform

The engagement was a success; SolGuruz completed four months worth of work in just one month. They guided the client through the best rollout plan and went the extra mile to keep everyone involved in the process. Overall, they were transparent, timely, communicative, and professional.

Arpan Garg's review for SolGuruz

Summarized from Arpan Garg's Clutch review

Arpan Garg, Founder, Commudle

IndiaIndia

Jun. 2023 - Aug. 2023
Software & SaaS

Custom Software Development - Mobile & Web Dev for Documentation Solutions Firm

SolGuruz's work continues to receive positive feedback from the client's customers. The team is highly communicative and professional from a project management standpoint, and internal stakeholders are impressed with the service provider's technical expertise.

Deepak Dhanak's review for SolGuruz

Summarized from Deepak Dhanak's Clutch review

Deepak Dhanak, Co-founder & CEO

IndiaMumbai, India

Sep. 2023 - Ongoing

From Our Portfolio

BNPL and Fintech Projects We Have Delivered

See how our team built BNPL and fintech products, from a full Buy Now Pay Later app to subscription billing and fractional investment platforms.

  • BNPL App development - Buy Now Pay Later App Development

    Buy Now Pay Later (BNPL) App Solution

    Get insights from FlexiPe App’s Case Study relates to the Buy Now Pay Later model, offering a comprehensive analysis of the BNPL App.

    Key Outcomes

    8-10 Month
    Delivery Timeline
    Full-Cycle
    Engagement Model
    3 Platforms
    Native iOS, Native Android, Web
  • UnSub: Subscription & Bill Management App

    How SolGuruz Built UnSub: A Subscription & Bill Management App

    SolGuruz designed and developed UnSub - a subscription and bill management platform delivering a complete cross-platform product across web and mobile in 8 weeks.

    Key Outcomes

    8-Week
    Delivery Timeline
    <2 Min
    to Add First Subscription
    2 Platforms
    iOS & Android
    Team of 5
    Engineers on Project
  • Fractional Real Estate Investment App

    Fractional Real Estate Investment App

    Explore our fractional real estate investment app case study, and how SolGuruz turned the complexity of shared property ownership into software people can actually use.

    Key Outcomes

    6-8 Week
    Delivery Timeline
    SPV
    Ownership Model
    iOS + Android
    Cross-Platform
    Global
    Investor Access
Build Your BNPL Platform With SolGuruz

We deliver secure, compliant, high-performance BNPL apps for iOS, Android, and web.

Related Fintech Software Services

Financial products rarely run on one platform. Explore the connected fintech software our team builds.

You are hereBNPL App Development

Frequently Asked Questions

Quick answers to the questions our clients and prospects ask most. If yours is not here, our team is one click away.

Jay Nandwana Technical Business Consultant at SolGuruz

Jay NandwanaSenior Technical Business Consultant

Need advice tailored to your project?

FAQs cover the common ground. For decisions specific to your tech stack, timeline, and team, talk to Jay and the team, who have shipped what you are planning.

A BNPL app development company builds the software behind instalment payments: the shopper app, the merchant checkout and API, and the credit decisioning, settlement, and collections underneath. SolGuruz builds all of it, and builds it to comply with the regulation that governs consumer credit.

Cost tracks scope. A lean first version with a simple Pay-in-4 flow and an integrated decisioning provider sits at the lower end, typically $30,000 to $50,000, and can reach an early launch in 2 to 4 months. A production-grade, regulated platform with native apps, a merchant console, in-house decisioning, and full compliance runs 8 to 14 months and costs several times more, often $150,000 to $300,000 or more. The biggest driver is how much of the credit and risk engine you build versus integrate.

A lean version can launch in a few months. A full, regulated BNPL platform typically takes 8 to 12 months from concept to production. SolGuruz delivered the FlexiPe BNPL app in 8 to 10 months.

A BNPL app is regulated consumer credit. In the US that means CFPB Regulation Z consumer protections, possible state money transmitter licensing for moving funds, mandatory KYC and AML checks, and PCI-DSS for any card data. We treat compliance as an architecture input from the start and build to comply.

Both approaches are valid. Many teams integrate a third-party underwriting or decisioning provider for the scoring model and build the limits, orchestration, and repayment lifecycle around it, while others build in-house for full control. This build-versus-integrate call is one of the biggest scope and cost decisions in a BNPL project, and we help you make it early.

Yes. If you do not want to become a lender, we integrate an existing BNPL provider or a white-label credit rail into your checkout. You keep your storefront and the provider carries the credit decisioning and risk. This is faster to market than building your own BNPL platform.

Yes. We built FlexiPe, a production BNPL app for a US-based fintech in Oakland, California, delivered in 8 to 10 months on native iOS and Android with a Python backend on AWS, against CFPB Reg Z, KYC and AML, and PCI-DSS Level 1 practices. It combines retail checkout BNPL with a utility-bill instalment flow in a single product.

We build custom BNPL products with the models that define apps like Klarna, Affirm, Afterpay, Zip, Sezzle, PayPal Pay Later, and Tamara, including Pay-in-4, monthly instalment financing, card-linked BNPL, and split payments. We tailor the plan types, decisioning, and merchant model to your product rather than cloning any single app.