SolGuruz Logo
Pricing

Lending Software Development Company

SolGuruz is a lending software development company that builds the systems lenders run on, from loan origination and underwriting to servicing, collections, and the borrower apps around them. We build the credit and risk engine, wire in the bureaus, and build to comply with the fair-lending rules that govern every loan.

Trusted by Startups and Enterprises Worldwide

Custom Software Development Success Stories

Hear It Directly From the Founders Who Built With Us

Real founders, CEOs, CTOs, and product owners behind 102+ shipped products across 14 industries share what working with SolGuruz looked like. Every story is one of 133+ independently verified client reviews across Clutch, Google, Glassdoor, and other platforms, averaging 4.9 ★★★★★ ratings.

Frame 01 / 04

Custom Software Solution Development / Driver Dashboard & Invoice Automation for Food Service Company

SolGuruz has delivered a solution that has reduced 90% of manual efforts through automation and provided real-time insights for supplier fulfillment and order volume trends. The team is responsive to requests and changes, and their proactive approach to problem-solving has stood out.

Summarized from Gary Boyd's Clutch review

Gary Boyd

CEO and Owner, Tasty Food Guys | Florida, USA

Read Clutch Verified Review
Tasty Food Guys

what we build

Lending Software Solutions We Build

Lending software is the pipeline of a loan: originate it, decide it, book it, service it, and collect it. From loan origination software development to loan management software development, we build each stage as a standalone system or one connected platform, tailored to the loan products you offer.

Loan Origination Systems (LOS)

Loan Origination Systems (LOS)

Loan origination software (LOS) for application intake, document collection, verification, and decisioning through to approval, so borrowers get an answer fast and your team is not chasing paperwork.

Loan Management Systems (LMS)

Loan Management Systems (LMS)

Loan management software that is the system of record for the loan book: balances, schedules, interest and fee accrual, statements, and a clean ledger finance and audit can trust.

Loan Servicing and Repayment

Loan Servicing and Repayment

Disbursement, repayment scheduling, auto-debit with retry logic, restructuring, and payoff, so the loan lifecycle runs without manual intervention.

Credit Decisioning and Scoring

Credit Decisioning and Scoring

Rules plus machine-learning models over bureau and alternative data, so you approve more good borrowers and price risk accurately, not on gut feel.

Collections and Recovery

Collections and Recovery

Delinquency workflows, dunning, restructuring offers, and recovery, with the compliance guardrails the FDCPA requires built into every step.

Digital Lending Platforms

Digital Lending Platforms

Digital-first lending, from a borrower applying on their phone to funds disbursed, with the whole journey automated and auditable.

P2P and Marketplace Lending

P2P and Marketplace Lending

Two-sided platforms that match borrowers with lenders or investors, with matching, funding, servicing, and payout routing handled cleanly.

Lending CRM and Broker Tools

Lending CRM and Broker Tools

Pipeline, borrower, and broker management so your origination channel sells and services loans without leaving the platform. When the CRM itself is the priority, our fintech CRM development team builds it as a standalone product.
Borrower Apps and Portals

Borrower Apps and Portals

Web and mobile self-service where borrowers apply, upload documents, track a loan, and pay, which cuts support load and lifts on-time repayment.

Ready to Build Your Lending Platform?

Talk to a team that builds origination, decisioning, and servicing software, and builds it to comply with the fair-lending rules.

our services

Our Lending Software Development Services

Our lending software development services cover the full build, from the first scoping call to post-launch iteration, so you are not stitching together separate vendors for app, credit engine, and compliance.

free resource

Building Lending Software? Start With the Complete Build Guide

Covers the whole fintech build: architecture, ledgers and reconciliation, PCI DSS, KYC/AML, GDPR, PSD2 and Open Banking, UX that balances security against friction, plus QA, fraud testing, and monitoring. Free to download.

19+ Downloads
FinTech App Development
Ebook

FinTech App Development: Building Secure Financial Software from Scratch

A practical eBook for founders, CTOs, and product leaders on building secure financial systems that users trust and regulators approve.

AI and ML

AI Capabilities We Build Into Lending Software

Lending is a data problem, so this is where AI pays off. We build it into decisioning and collections, with a human in the loop and an audit trail for every model, backed by our AI development team.

AI Credit Decisioning

  • Approve or decline in real time using bureau data and machine-learning models, not just static cutoffs.
  • Approve more good borrowers and price risk accurately while keeping defaults in check.

Alternative-Data Scoring

  • Score thin-file and new-to-credit applicants from cash-flow, transaction, and open-banking data.
  • Reach borrowers a traditional bureau score would reject, without taking on blind risk.

Fraud Detection

  • Flag synthetic identities, first-party fraud, and risky applications at the point of application.
  • Cut fraud losses before the loan is ever booked.

Collections and Default Prediction

  • Predict which loans are likely to slip before the due date and prioritize outreach.
  • Time the right nudge on the right channel to lift recovery and lower charge-offs.

Document AI for Loan Intake

  • Extract and verify income, identity, and asset data from documents during application.
  • Turn a paperwork-heavy origination into minutes, with the verification checks intact.

Conversational Borrower Support

  • Answer balance, payoff, and payment questions with an assistant that knows the loan context.
  • Reduce servicing calls while keeping answers accurate and compliant.
Put AI to Work in Your Lending Platform

From sharper credit decisions to smarter collections, we build the AI that improves your approval and default numbers at once.

compliance

Compliance We Build To

Lending is one of the most regulated things software can do, from fair lending to disclosures to collections. We treat compliance as an architecture input from day one and build to comply rather than bolting it on. For the deeper view, read our fintech secure product building playbook.

FCRA and Fair Credit Reporting

FCRA and Fair Credit Reporting

We build the consent, adverse-action, and dispute flows the Fair Credit Reporting Act requires when you pull and act on credit data.

ECOA and Fair Lending

ECOA and Fair Lending

We build decisioning that is explainable and testable for disparate impact, so your credit models support Equal Credit Opportunity Act obligations rather than hiding bias.

TILA, Regulation Z, and Disclosures

TILA, Regulation Z, and Disclosures

APR, fee, and payment disclosures generated correctly and on time, with the records to prove it, because a disclosure error is a compliance error.

Data Security, GLBA, and SOC 2

Data Security, GLBA, and SOC 2

Encryption, access control, and audit logging to GLBA safeguards and SOC 2-aligned practices, with ISO 27001 and ISO 9001 certified processes behind delivery. For the detail, see our answer on security requirements for fintech apps.

Building Lending Software for Australia

Australian lenders work under their own credit reporting regime, responsible lending law, and real-time payment rails, so we build each one into the platform from the start.

Comprehensive Credit Reporting (CCR)

Australia's comprehensive credit reporting system shares positive data, including 24 months of repayment history, alongside defaults. Since 1 July 2022, lenders also report financial hardship information, which credit reporting bodies cannot use to calculate a credit score. We build the monthly reporting feeds, hardship flags, and correction workflows that Part IIIA of the Privacy Act requires.

NCCP Responsible Lending Obligations

Chapter 3 of the National Consumer Credit Protection Act requires lenders to make reasonable inquiries about a borrower's requirements, objectives, and financial situation, verify it, and assess the loan as not unsuitable before approving. We build those responsible lending obligations into origination, with a stored record for every decision and a copy ready when a borrower asks.

integrations

Integrations a Lending Platform Depends On

A lending platform is a decision engine wrapped in integrations. These are the connections we wire in so you can verify, decide, and disburse in one clean flow.

Credit Bureaus and Scoring

Credit Bureaus and Scoring

Experian, Equifax, and TransUnion for pulls and, where applicable, repayment reporting, plus alternative-data providers for thin-file applicants.

KYC, Identity, and Fraud

KYC, Identity, and Fraud

Identity verification, KYC and AML screening, and fraud signals wired into application, so credit is only extended to a verified borrower.

Open Banking and Bank Data

Open Banking and Bank Data

Plaid, MX, and similar providers for cash-flow underwriting and income verification straight from the applicant bank account.

Payments and Core Banking

Payments and Core Banking

Disbursement rails, auto-debit and card payment for repayments, and core-banking or ledger systems, so money in and money out both reconcile.

NPP, Osko, and PayTo

NPP, Osko, and PayTo

Australia's New Payments Platform settles payments in real time, around the clock, with Osko handling instant account-to-account transfers. We use it to disburse loan funds in real time and build PayTo agreements for repayments, which give borrowers control of the mandate as the industry moves off the batch-based BECS system.

how to build

Custom Build, Modernize, or Accelerate

You do not always need to rip out the core. The right move depends on how much of your edge is in the lending logic and how much legacy origination and servicing you run, and we help you choose before the budget is set.

Custom Build

Custom Build

The right choice when your credit policy or borrower experience is the differentiator: a bespoke origination, decisioning, and servicing stack built to your loan products.

Modernize the Legacy Core

Modernize the Legacy Core

When a legacy LOS or servicing system is slowing you down, we re-architect, extend, or wrap it with modern services and borrower apps without losing the loan book.

Lending Accelerator

Lending Accelerator

When speed to market wins, we build on proven components and open-banking rails to reach a compliant lending MVP faster, then extend it as volume grows.

Tech Stack We Use for Lending Software

We keep the stack proven and auditable, because a lending platform is won on decisioning accuracy and compliance, not on chasing trends.

Our Lending Software Development Process

We run a defined process so fair-lending compliance and credit-model integrity are settled early, not late. Every stage lands a named deliverable with a clear owner.

  1. 01 / 05

    Discovery and Compliance Mapping

    We define the loan products, borrower segments, and states, and map the FCRA, ECOA, and TILA obligations for each, because lending regulation shapes the scope from the start.

    Deliverables: A compliance obligations map for each loan product, covering FCRA, ECOA, and TILA, or the NCCP Act and credit reporting rules for Australia, plus borrower segment definitions and a scoped module list.
  2. 02 / 05

    Architecture and Credit Policy

    We lock the modules, the build-versus-buy calls, the budget, and the release scope, then design the services around the credit policy and a ledger finance can trust.

    Deliverables: An architecture document, the credit policy rules specification, the ledger and data model, and a line-item estimate with the release plan.
  3. 03 / 05

    Design and Development

    We design the borrower, underwriter, and collections flows, then build the origination, decisioning, and servicing modules with bureau, KYC, and open-banking integrations wired in and security first.

    Deliverables: Figma designs for borrower, underwriter, and collections flows, working builds demoed every two weeks, integration specs for bureaus, KYC, and open banking, and full code repository access from day one.
  4. 04 / 05

    Testing and Compliance QA

    We test decisioning accuracy, the full loan lifecycle including delinquency paths, and performance under load, and verify controls against FCRA, ECOA, TILA, and SOC 2-aligned practices.

    Deliverables: Decisioning accuracy and fair-lending test reports, end-to-end loan lifecycle results including delinquency paths, load test results, and a compliance controls checklist.
  5. 05 / 05

    Launch and Optimization

    We migrate the loan book, onboard the first borrowers and channels, and stand up monitoring, then tune approval rates, default rates, and collections as real loans flow through the platform.

    Deliverables: A migrated and reconciled loan book, a launch runbook, monitoring dashboards for approval, default, and collections rates, and a post-launch tuning report.

AI-native engineering

Our AI-Native Engineering Standards

AI-native by practice, engineer-led by principle. We use AI-assisted tools at every step of design, development, launch and growth, and a senior engineer still owns every architecture decision, every security review and every line that reaches production.

  1. 01Design

    • AI-Assisted Discovery and Prototyping

      We use AI to map requirements, user stories and workflows, and to turn them into a clickable prototype your stakeholders can test before production code is written.

      Engineer-ledOur team runs discovery with you and agrees the scope before anything is built.

    • Pixel-Perfect UI/UX and Design Systems

      AI speeds up layout variations, accessibility checks and design-to-code handoff, on a shared design system in Figma.

      Engineer-ledDesigners make every design decision, and every screen is built to match the approved design on every device.

    • Architecture-First Planning

      We settle the architecture, data model, state management and integrations before the build starts, so the product scales without a rewrite.

      Engineer-ledA senior engineer owns every architecture decision.

  2. 02Build

    • AI-Assisted Development, Human-Owned Code

      Our developers use Claude Code, GitHub Copilot and Cursor for scaffolding, boilerplate and repetitive patterns.

      Engineer-ledSenior engineers own the logic, and a developer reviews every AI-generated change.

    • Coding Standards, Git Flow and Peer Review

      Code follows agreed standards and a Git Flow branching model, and AI-powered review flags issues on every commit.

      Engineer-ledA second developer reviews every change before it merges.

    • Secure and Compliant by Default

      We work under ISO 27001 and ISO 9001 certified processes, build to SOC 2-aligned controls, and add HIPAA-aligned safeguards where health data is involved.

      Engineer-ledA senior engineer owns every security review. Independent security agencies run penetration tests, and we remediate their findings.

  3. 03Ship

    • AI-Generated Tests and Manual QA

      AI generates unit tests, edge cases and regression suites from the codebase.

      Engineer-ledQA engineers test the real user flows by hand before every release.

    • Static Analysis and CI/CD Pipelines

      Static code analysis scans every commit, and CI/CD pipelines build, test and deploy across development, staging and production.

      Engineer-ledEngineers set the quality gates the pipeline enforces and fix what the scans flag.

    • Phased, Monitored Releases

      Alpha and beta builds go to internal and external users first, and releases roll out in phases with a rollback plan.

      Engineer-ledYou get a demo build after every sprint and review it with the team.

  4. 04Grow

    • Monitoring, Analytics and Performance

      Crash reporting, performance monitoring and usage analytics are in place from launch day, and for mobile apps we track Google Play and App Store analytics too.

      Engineer-ledOur engineers keep checking crash reports and store analytics for the life of the product, so it stays stable long after launch.

    • Data-Driven Iteration and Growth

      We plan in two-week sprints and prioritise new features from user feedback and analytics, not guesswork. For clients without an in-house marketing team, we also run the product growth strategy after launch.

      Engineer-ledDaily stand-ups and sprint demos keep you in every decision about what ships next.

    • Documentation, Ownership and Ongoing Support

      AI keeps API references and technical docs in sync with the code, and maintenance plans keep the product secure and up to date.

      Engineer-ledYou get full repository access and IP ownership, and one in-house senior team stays accountable for the outcome.

cost

How Much Does Lending Software Development Cost?

Lending software development cost tracks scope more than anything else, and the biggest driver is how much of the credit and risk engine you build versus integrate. A focused module can launch in 2 to 4 months, typically $30,000 to $50,000. A full platform with origination, decisioning, and servicing runs 8 to 14 months, often $150,000 to $300,000 or more.

Focused Module MVP

Focused Module MVP

One module, such as an origination flow or a borrower app, on an integrated decisioning provider. The fastest route to lending live with real borrowers. Typically $30,000 to $50,000.

Growth Lending Platform

Growth Lending Platform

Origination and servicing with integrated decisioning, several integrations, and core compliance. Typically $50,000 to $150,000.

Full Lending Platform

Full Lending Platform

Origination, in-house decisioning, servicing, collections, and compliance automation. The build for a lender running its book on the software. Typically $150,000 to $300,000 or more.

Cost Drivers

Cost Drivers

Number of modules and loan products, the build-versus-integrate call on decisioning, the depth of bureau and open-banking integrations, and the compliance scope across states.

Ranges are indicative and depend on your loan products, integrations, and compliance scope. We give a line-item estimate during scoping.

Build a Lending Platform That Actually Scales

From the credit engine to servicing and compliance, we build lending software for banks, fintech lenders, and marketplaces.

lending types

Lending Types We Build For

A consumer personal-loan flow and an SME line of credit are different products with different rules. We build for the loan types you actually offer.

Consumer Lending

Consumer Lending

Personal loans, installment credit, and point-of-sale financing with fast, fair, and compliant decisioning for individual borrowers.

SME and Commercial Lending

SME and Commercial Lending

Business loans, lines of credit, and invoice and revenue-based financing, with the underwriting depth commercial credit demands.

Mortgage and Home Lending

Mortgage and Home Lending

Origination, document-heavy underwriting, and servicing for mortgage and home-equity products, built for the disclosure rules these loans carry.

Auto and Equipment Finance

Auto and Equipment Finance

Point-of-sale and dealer financing for auto and equipment, with rate cards, dealer portals, and servicing tuned to secured lending.

P2P and Marketplace Lending

P2P and Marketplace Lending

Two-sided platforms matching borrowers with lenders or investors, with funding, servicing, and payout routing handled cleanly.

BNPL and POS Financing

BNPL and POS Financing

Buy Now Pay Later and checkout instalments, a lending product of its own. See our dedicated BNPL app development work.

who we serve

Who We Build Lending Software For

A bank modernizing an origination core and a fintech launching a new loan product need very different builds. We build for lenders across the market.

Banks and Credit Unions

Banks and Credit Unions

Origination modernization and digital borrower front ends for banks and credit unions that need to move faster without replacing the core.

Fintech Lenders

Fintech Lenders

Full digital lending platforms and MVPs built to comply, for fintechs launching a new loan product on modern, API-first rails.

P2P and Marketplace Lenders

P2P and Marketplace Lenders

Two-sided platforms with matching, funding, servicing, and investor payouts for peer-to-peer and marketplace lending models.

Microfinance and Community Lenders

Microfinance and Community Lenders

Lean, mobile-first origination and servicing for microfinance institutions and community lenders serving thin-file borrowers.

Auto and Equipment Financiers

Auto and Equipment Financiers

Dealer and point-of-sale financing platforms with rate cards, dealer portals, and secured-lending servicing.

Mortgage Lenders

Mortgage Lenders

Document-heavy origination, underwriting, and servicing built for the disclosure and compliance load of home lending.

Why SolGuruz for Lending Software Development?

We combine shipped lending experience, real compliance discipline, and one team across the whole build, so you build with a team that has taken a credit product to production before.

Here's why lenders trust us to build their platform:

  • A Shipped Lending Product

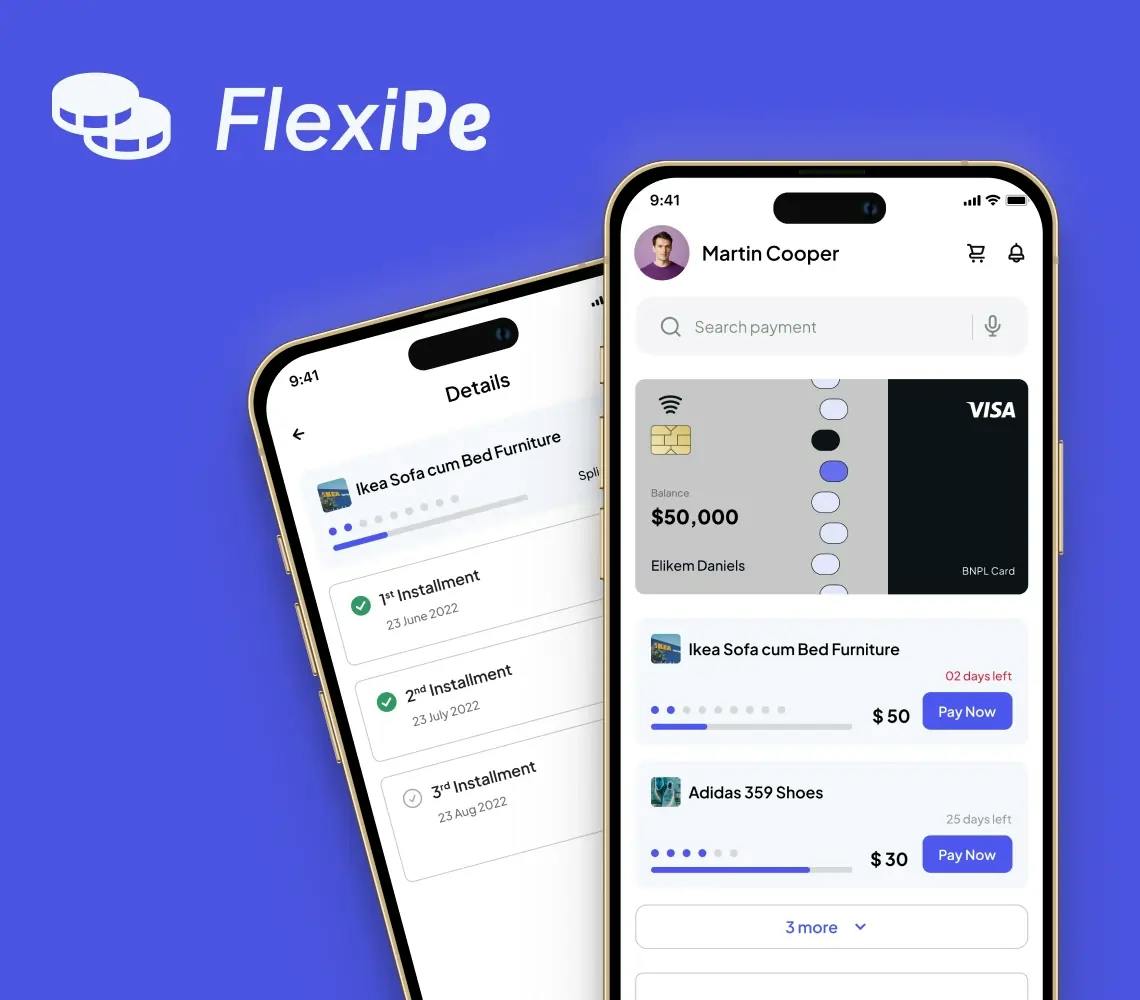
    We built and launched FlexiPe, a production BNPL lending product, with real-time decisioning, repayments, and collections, so we scope your build from delivery, not theory.
  • Compliance Built In

    We build to comply with FCRA, ECOA, TILA and Reg Z, FDCPA, and GLBA in the US, and with the NCCP Act and credit reporting rules in Australia, so the fair-lending and disclosure parts are handled from the architecture up.
  • The Credit Engine, Not Just the App

    We build the decisioning, scoring, servicing, and collections that make a lending product work, which is where most teams underestimate the effort.
  • Proven Delivery

    SolGuruz has shipped 102+ products across 14 industries with a 99.9% delivery rate, backed by ISO 27001 and ISO 9001 certified processes.
  • One Team, One Build

    Origination, decisioning, servicing, and compliance under one roof, so you are not integrating separate vendors and hoping the seams hold.

What Our Clients Say

Read what founders and product teams say about building with SolGuruz.

Top Clutch Software Developers - Financial Services, Ahmedabad
Top Clutch Software Developers - Financial Services, India
Top Clutch App Development Company - Financial Services, Ahmedabad
Top Clutch Web Developers - Financial Services, Ahmedabad
Clutch Fall Champion 2024
Software & SaaS

SaaS Platform Redesign Services for Sales Promoting Platform

The platform looks better than before and is appreciated by the end customers, thanks to SolGuruz. The team uses Slack for communication and has been effective so far. Their dedication and proactivity impress the client.

Robin Singhvi's review for SolGuruz

Summarized from Robin Singhvi's Clutch review

Robin Singhvi, CEO, SmartCue

IndiaMumbai, India

Jan. 2022 - Ongoing
Software & SaaS

UI/UX Design & Development for Software Community Platform

The engagement was a success; SolGuruz completed four months worth of work in just one month. They guided the client through the best rollout plan and went the extra mile to keep everyone involved in the process. Overall, they were transparent, timely, communicative, and professional.

Arpan Garg's review for SolGuruz

Summarized from Arpan Garg's Clutch review

Arpan Garg, Founder, Commudle

IndiaIndia

Jun. 2023 - Aug. 2023
Software & SaaS

Custom Software Development - Mobile & Web Dev for Documentation Solutions Firm

SolGuruz's work continues to receive positive feedback from the client's customers. The team is highly communicative and professional from a project management standpoint, and internal stakeholders are impressed with the service provider's technical expertise.

Deepak Dhanak's review for SolGuruz

Summarized from Deepak Dhanak's Clutch review

Deepak Dhanak, Co-founder & CEO

IndiaMumbai, India

Sep. 2023 - Ongoing

From Our Portfolio

Fintech Projects We Have Delivered

See how our team built regulated fintech and lending products, from the FlexiPe BNPL app to subscription billing and a fractional investment platform.

  • Fractional Real Estate Investment App

    Fractional Real Estate Investment App

    Explore our fractional real estate investment app case study, and how SolGuruz turned the complexity of shared property ownership into software people can actually use.

    Key Outcomes

    6-8 Week
    Delivery Timeline
    SPV
    Ownership Model
    iOS + Android
    Cross-Platform
    Global
    Investor Access
  • UnSub: Subscription & Bill Management App

    How SolGuruz Built UnSub: A Subscription & Bill Management App

    SolGuruz designed and developed UnSub - a subscription and bill management platform delivering a complete cross-platform product across web and mobile in 8 weeks.

    Key Outcomes

    8-Week
    Delivery Timeline
    <2 Min
    to Add First Subscription
    2 Platforms
    iOS & Android
    Team of 5
    Engineers on Project
  • BNPL App development - Buy Now Pay Later App Development

    Buy Now Pay Later (BNPL) App Solution

    Get insights from FlexiPe App’s Case Study relates to the Buy Now Pay Later model, offering a comprehensive analysis of the BNPL App.

    Key Outcomes

    8-10 Month
    Delivery Timeline
    Full-Cycle
    Engagement Model
    3 Platforms
    Native iOS, Native Android, Web
Build Your Lending Platform With SolGuruz

We deliver secure, compliant, high-performance lending software for banks, fintech lenders, and marketplaces.

Related Fintech Software Services

Financial products rarely run on one platform. Explore the connected fintech software our team builds.

You are hereLending Software Development

Frequently Asked Questions

Quick answers to the questions our clients and prospects ask most. If yours is not here, our team is one click away.

Jay Nandwana Technical Business Consultant at SolGuruz

Jay NandwanaSenior Technical Business Consultant

Need advice tailored to your project?

FAQs cover the common ground. For decisions specific to your tech stack, timeline, and team, talk to Jay and the team, who have shipped what you are planning.

A lending software development company builds the systems lenders run on: loan origination, credit decisioning, loan management and servicing, collections, and the borrower apps and portals around them. SolGuruz builds these and builds them to comply with the fair-lending rules that govern consumer and commercial credit.

Cost tracks scope. A focused module such as an origination flow or a borrower app on an integrated decisioning provider sits at the lower end, typically $30,000 to $50,000, and can launch in 2 to 4 months. A full platform with in-house decisioning, servicing, collections, and compliance automation runs longer and costs several times more, often $150,000 to $300,000 or more. The biggest driver is how much of the decisioning and servicing you build in-house versus integrate.

A single lending module goes live in 2 to 4 months. A full, multi-module platform takes 8 to 14 months, depending on the loan products, the depth of bureau and open-banking integrations, and the number of markets in scope.

It depends on where your edge sits. When the credit policy is your differentiator, we build decisioning in-house so you own the models and rules. When speed matters more, we integrate a scoring provider, build origination and servicing around it, and leave a path to bring decisioning in-house later.

Lending is heavily regulated. Software typically needs to support FCRA for credit data, ECOA fair-lending rules, TILA and Regulation Z disclosures, FDCPA for collections, GLBA data-security safeguards, plus state lending licenses and data-privacy laws. We treat these as architecture inputs and build to comply from the start.

Australian lending platforms need comprehensive credit reporting feeds with hardship flags, responsible lending checks under the NCCP Act, and an Australian Credit Licence holder behind them. We typically pair these with real-time NPP disbursement and PayTo repayments.

Yes. We build loan origination systems, credit decisioning and scoring, loan management and servicing, collections and recovery, lending CRM, and borrower apps, as standalone modules or as one connected platform, tailored to your loan products.

Yes. We integrate Experian, Equifax, and TransUnion for credit data, KYC and AML and fraud providers for identity, and Plaid and similar open-banking providers for cash-flow underwriting, plus payment rails and core-banking systems for disbursement and repayment.

Yes. BNPL and point-of-sale financing are lending products, and we have shipped one in production. For that specific model see our dedicated BNPL app development work; for a broader lending platform, BNPL can be one product line within it.